
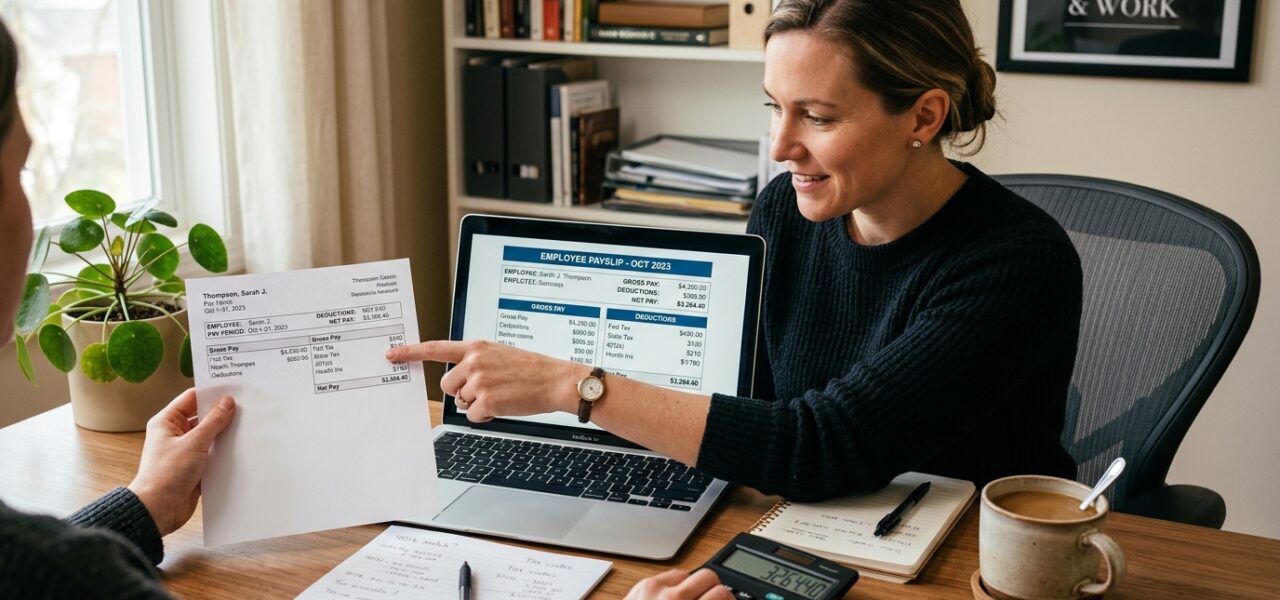
Most employees glance at the “net pay” number at the bottom of their salary slip and move on. The rest of the document — the dense rows of deductions, withholdings, and codes — gets ignored as incomprehensible bureaucracy. This is a mistake. Understanding every line of your paycheck gives you the knowledge to verify you are being paid correctly, optimize your tax withholding, and make informed decisions about benefits enrollment.
Gross Pay vs. Net Pay
Gross Pay is your total compensation before any deductions — your salary or hourly rate times hours worked, plus any overtime, bonuses, or commissions. If your annual salary is $72,000, your bi-weekly gross pay is $72,000 ÷ 26 = $2,769.23.
Net Pay (take-home pay) is what remains after all mandatory and voluntary deductions. The difference between gross and net is typically 20–40% depending on your tax bracket and benefit elections.
Mandatory Deductions
Federal Income Tax Withholding: Calculated based on your W-4 elections. The amount varies by your filing status, claimed dependents, and additional withholding elected. If you consistently receive a large refund or owe a large amount at tax time, update your W-4 with your employer — ideally, you want to owe little and receive little back (that refund is an interest-free loan to the government).
State Income Tax: Varies by state. Nine states have no state income tax (Texas, Florida, Nevada, Washington, Wyoming, Alaska, South Dakota, Tennessee, New Hampshire). Others range from 2.9% (North Dakota) to 13.3% (California top rate).
Social Security Tax: 6.2% of your gross wages up to the annual wage base ($168,600 in 2024). Once you earn above this threshold, Social Security withholding stops for the year. Your employer pays a matching 6.2%.
Medicare Tax: 1.45% of all wages — no cap. High earners (above $200,000 single / $250,000 married) pay an additional 0.9% Additional Medicare Tax on wages above those thresholds.
Pre-Tax Deductions: Where Optimization Lives
Pre-tax deductions reduce your gross pay before taxes are calculated — making them doubly valuable.
- 401(k) contributions: Traditional 401(k) contributions reduce your federal (and usually state) taxable income dollar for dollar. Contributing $500/month to your 401(k) at a 22% federal tax bracket saves $110/month in federal income tax — effectively reducing the real cost of saving $500 to $390.
- Health insurance premiums: Employer-sponsored health, dental, and vision insurance premiums paid through payroll are typically pre-tax under a Section 125 cafeteria plan — reducing your taxable income.
- Health Savings Account (HSA) contributions: If enrolled in an HDHP, HSA payroll contributions are pre-tax — the most tax-efficient savings vehicle available.
- Flexible Spending Account (FSA): Pre-tax contributions for qualified medical or dependent care expenses.
Post-Tax Deductions
Some deductions are taken after tax — they do not reduce your taxable income but still reduce your take-home pay:
- Roth 401(k) contributions (post-tax now, tax-free in retirement)
- Supplemental life insurance above employer-paid amounts
- Wage garnishments (court-ordered debt repayments)
- Union dues
Use our salary calculator to see a detailed breakdown of your estimated take-home pay at any gross salary level, including all major deductions.
This article is for educational purposes only. Please consult a qualified financial advisor for personalized guidance.