
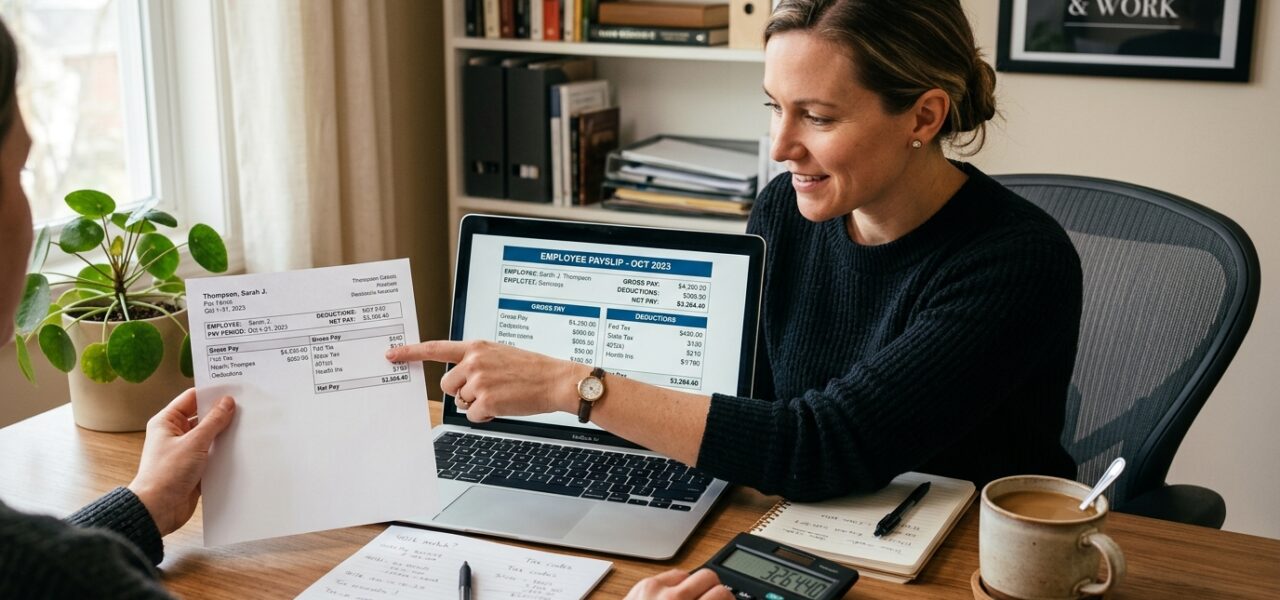
The transition from employee to self-employed is one of the most financially transformative changes a person can make — in both directions. The freedom and income potential of freelancing, consulting, and gig work are real and significant. But so are the financial responsibilities that most employees have never thought about because their employer handled everything invisibly. Self-employment taxes, quarterly estimated payments, business deductions, and retirement contributions without employer match are all responsibilities that now land entirely on your shoulders. Understanding them is not optional; it is the price of admission for financial sustainability as an independent worker.
The Self-Employment Tax: Why Freelancers Pay More Than Employees
When you are employed by a company, your FICA taxes (Social Security and Medicare) are split equally between you and your employer. You see 6.2 percent Social Security and 1.45 percent Medicare deducted from your paycheck — a total of 7.65 percent. Your employer quietly matches that amount, paying another 7.65 percent to the IRS on your behalf. As a self-employed person, you are both the employee and the employer. You pay both halves of FICA — the full 15.3 percent on your net self-employment income (12.4 percent Social Security up to the $168,600 wage base and 2.9 percent Medicare with no cap, plus an Additional Medicare Tax of 0.9 percent on income above $200,000).
This means a self-employed person earning $80,000 in net profit pays approximately $11,304 in self-employment tax before any federal or state income tax is calculated. This frequently shocks new freelancers who compare their hourly rate to their former employee salary without accounting for this additional tax burden.
The Deduction That Softens the Blow
To partially compensate for the self-employment tax burden, the IRS allows you to deduct half of your self-employment tax from your gross income before calculating federal income tax. On $80,000 of self-employment income with $11,304 in self-employment tax, you deduct $5,652 from your gross income — saving approximately $1,243 in federal income tax at the 22 percent bracket. This is a meaningful but partial offset; the net effective burden of self-employment tax remains significantly higher than for equivalent employees.
Quarterly Estimated Tax Payments: The Schedule Most Freelancers Miss
Employees have taxes withheld automatically with every paycheck, ensuring taxes are paid to the IRS throughout the year. Self-employed workers must replicate this system manually by making quarterly estimated tax payments. The IRS requires these payments if you expect to owe at least $1,000 in federal income taxes for the year. The four payment due dates are: April 15 (for January through March income), June 15 (April and May), September 15 (June through August), and January 15 of the following year (September through December).
Missing these deadlines or underpaying quarterly estimates triggers an underpayment penalty — currently calculated at the federal funds rate plus 3 percent, applied to the unpaid amount for each day it is late. While the penalty rate seems modest, it adds up over the course of a year and compounds the financial stress of a large April tax bill with additional penalty charges. A simple system: set aside 25 to 30 percent of every payment you receive into a dedicated tax savings account and pay the quarterly estimates from that account on schedule.
Business Deductions: Legally Reducing Your Self-Employment Tax Base
Unlike employees who can claim very few work-related deductions, self-employed workers can deduct legitimate business expenses from their gross income — reducing not only income tax but also the self-employment tax base. Commonly missed deductions include: home office deduction (dedicated workspace), vehicle mileage for business purposes (65.5 cents per mile in 2023), health insurance premiums for self and family (full deduction from income), retirement contributions to a SEP-IRA or Solo 401(k), professional development, industry subscriptions and tools, software and technology expenses, professional services (accountant, lawyer), and business portion of phone and internet costs.
Each deductible dollar not only reduces income tax but also reduces the self-employment tax base — effectively giving you a 15.3 percent bonus deduction on top of whatever income tax savings you receive. This is why meticulous expense tracking is not a minor administrative task for self-employed workers — it has direct and meaningful impact on your total tax liability.
Retirement Accounts for the Self-Employed: Your Most Powerful Tax Tool
Self-employed workers lack employer-sponsored 401(k) plans but have access to retirement savings vehicles that are often more generous: the SEP-IRA allows contributions of up to 25 percent of net self-employment income up to $69,000 for 2024. The Solo 401(k) allows both an employee contribution ($23,000, or $30,500 if 50+) and a profit-sharing employer contribution of up to 25 percent of net earnings, with a combined maximum of $69,000 — offering higher contribution limits than the SEP-IRA for self-employed workers with moderate income. Every dollar contributed to a SEP-IRA or traditional Solo 401(k) reduces your taxable income and your self-employment tax base, making these accounts exceptionally powerful tax-reduction tools beyond their retirement savings function.
This article is for educational purposes only and does not constitute financial advice. Please consult a qualified financial professional for personalized guidance.